A Friendly and Relaxing place to stay in the heart of St Davids
Close to The Pembrokeshire Coast Path, The Cathedral and all shops, pubs, and restaurants
Bryn Awel, St Davids
Central St Davids location close to the tourist information centre
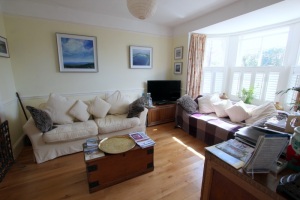
Our Guest Lounge
A comfortable place to sit and relax
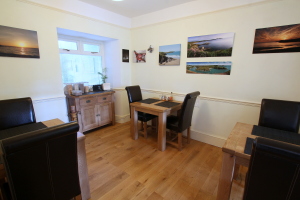
The Breakfast Room
A friendly & relaxing environment
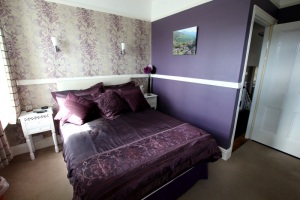
A Guest Bedroom
All rooms recently decorated and all with en-suite bathrooms
Your money when a casino closes
The money in your casino balance feels like yours. In law it belongs to the operator, and you hold an IOU. That distinction decides where you sit in the queue when a company runs into trouble, and whether your balance comes back at all.
Deposit £50 at a UK-licensed casino and the operator credits your account and takes ownership of the cash. Your claim now sits against the business as a whole. The UKGC requires every licensed operator to tell you how well that claim is protected before you sign up, and the answer varies from one site to the next.
Where your deposit sits
Money leaves your bank and lands in the operator's trading accounts. From there it mixes with staff wages, marketing budgets, licence fees and the money set aside for other players' withdrawals. Unless an operator takes specific steps to separate customer cash, every player's balance shares the same pot.
Pooling holds up while a company trades. The arrangement fails in insolvency, when an administrator freezes the accounts and builds a list of everyone owed money. You appear on that list without security, and you wait behind lenders, landlords and tax authorities.
Some operators go further. They hold player funds in a trust account, or they buy insurance that covers the shortfall if the business fails. That is the gap between a balance you can recover and a balance you write off.
A balance built from bonus funds works differently again. Bonus credit carries no cash value under most terms and conditions, and administrators treat it as promotional credit instead of a debt. Money sitting in a pending withdrawal is the riskiest position of all. The operator has taken it from your balance but has not sent it to your bank, which leaves it inside the estate.
The three funds protection labels
The UKGC requires operators to publish a funds protection rating, and it groups them into three levels.
Not protected. Player money forms part of the company's general assets. If the operator fails, you claim as an unsecured creditor and you take whatever remains after the secured creditors collect.
Medium protection. The operator holds player funds separately or carries insurance against failure, but conditions attach to the arrangement. A collapse might leave part of your balance uncovered.
High protection. Player funds sit in a separate account held by an unconnected trustee, or the operator insures them so they stay available if the business fails. This label gives your claim the best chance of being met in full.
Verify the label rather than trusting a claim in a welcome banner. The rating should sit next to the operator's licence number and the UKGC logo, and it should use the Commission's own wording. If a site describes its protection in vague terms and never names a trustee or insurer, treat the money as unsecured.
You will find the rating on the operator's homepage, close to the licence details and the footer links. Check it before you deposit. The check takes under a minute, and it tells you more about the safety of your balance than any welcome offer does.
What happens when an operator fails
Administrators take control, trading stops and withdrawals freeze. The team assembles a creditor list and works out what the estate can pay. Player balances rank as unsecured debts unless a trust or insurance structure covers them.
The timeline runs long. Administrators need months to establish the size of the shortfall, and creditors wait through a statutory process before any distribution happens. You cannot speed it up by complaining to the operator, because the operator no longer controls the assets. The UKGC can act on licence breaches, but it does not hold your money and it cannot order a payout from an insolvent estate.
Where the compensation gap sits
The Financial Services Compensation Scheme stays out of it. The FSCS protects bank deposits, insurance policies and certain investments, up to £85,000 per person per institution. Gambling balances fall outside its scope, so the safety net under your current account does not follow your money into a casino account.
The Football Index precedent
Football Index showed how this plays out. Customers treated their balances and dividend positions as investments, and the business entered administration in 2021 with hundreds of millions of pounds frozen. Most people recovered a fraction of what they held. After that collapse, the UKGC rewrote how operators describe the risk to customers.
What the regulator changed
The Gambling Commission consulted on player fund protection and tightened its requirements. Operators must now describe how they hold customer money in plain English, and they must display the rating on their site. The rules exist to stop players treating a casino balance like a bank account, because the two are not the same thing.
A licence from the UKGC means an operator meets standards on fairness, complaints handling and responsible gambling tools. It does not insure your deposit against business failure. Read the funds protection label as the part of the licence that deals with your money.
What you can do about it
A few habits limit the damage if your operator collapses.
Withdraw winnings instead of letting a balance build up. Cash in your bank account carries FSCS cover; cash in a casino account carries whatever protection the operator has arranged. The safest place for your money is outside the site.
Check the funds protection rating before you open an account, and weigh it the way you weigh a licence number. Buran Casino online lists its rating next to its UKGC licence details, which lets you see the arrangement before you commit a deposit.
Watch withdrawal times. An operator that pays out in hours is easier to stay clear of than one that takes days, because you can move funds before news of trouble spreads. Debit cards, PayPal, Apple Pay and open banking transfers all reach UK casino accounts. None of them change the fact that your balance belongs to the company until it lands back in your bank. The Gambling Commission barred credit cards from UK gambling deposits in April 2020, so you will not see them offered.
Play across more than one operator if you deposit often. If one firm hits trouble, the rest of your money stays within reach.
Keep your own records. Download statements from your account each month and save the confirmation emails for every deposit and withdrawal. If an administrator asks you to prove a balance, those documents settle the question, and a screenshot of your balance on the day trading stopped helps as well.
If your operator goes under
Move first and ask questions after. A failing operator can block withdrawals before it says anything in public, so a stalled payout is your early warning. Try to withdraw the moment a normal request fails.
Check the operator's licence status on the UKGC website. If the Commission has suspended the licence, administrators have taken over, and the site should carry a notice explaining the position.
Register as a creditor with the administrator. You will need records of your balance, deposits and withdrawals, and your bank statements will support the claim. Recovery takes months and the payout falls short of what you held, but the paperwork puts you in line.
Report the operator to the UKGC as well. The Commission tracks complaints and acts on patterns of withheld funds.
Keep the risk in perspective
Chasing a frozen balance can push you into depositing more somewhere else, which makes a bad situation worse. GamStop lets you block yourself from every UK-licensed operator for a period you choose, and BeGambleAware runs free support and a helpline for anyone who needs it.